Motor truck cargo insurance in Texas: what it covers and what it doesn't
Cargo coverage is the line item brokers check first. Here's what motor truck cargo insurance actually pays for, the exclusions that surprise carriers, and how much limit you really need.
Why cargo coverage is the first thing brokers ask about
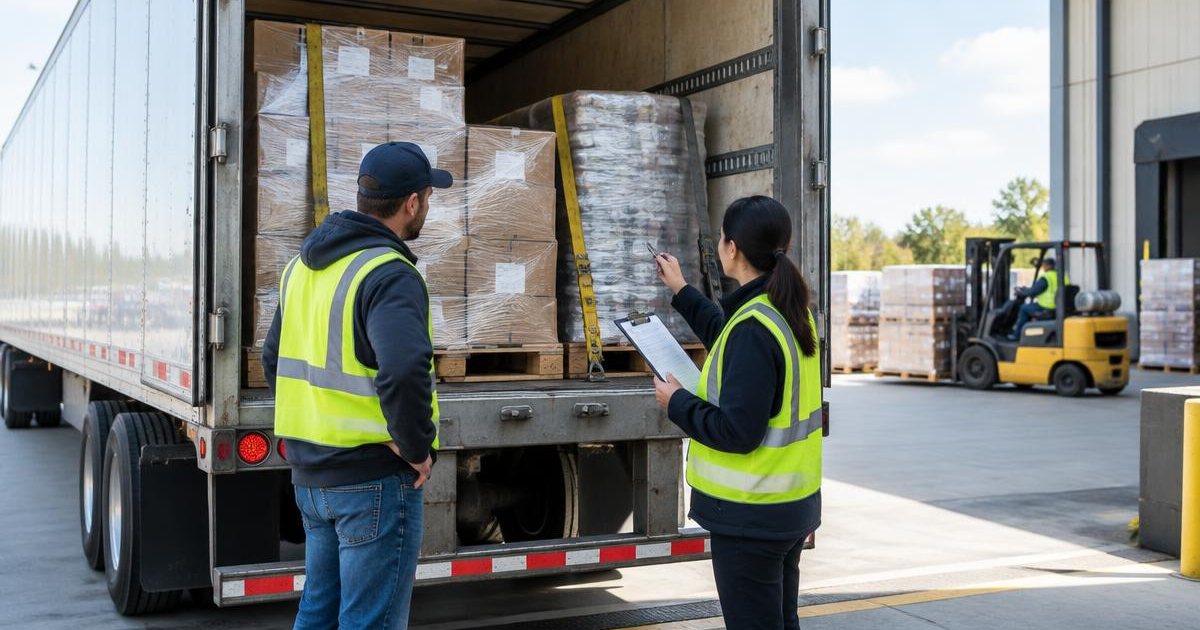
You can have a spotless driving record and a brand-new tractor, but if your motor truck cargo policy doesn't meet the broker's requirements, you don't get the load. Cargo insurance protects the freight you're hauling — and it protects you from a six-figure bill when something goes wrong on the road.
What motor truck cargo insurance covers
A standard cargo policy pays when freight in your care, custody, and control is damaged or lost due to:
- Collision or overturn — the most common cargo claim by far.
- Theft — full truckload theft is a growing problem at Texas truck stops and drop lots.
- Fire, lightning, and weather — including hail and flood damage to the load.
- Loading and unloading accidents — if your policy includes this endorsement. Not all do.
The exclusions that get carriers in trouble
This is where claims get denied. Read your policy for these before you sign:
- Reefer breakdown. If you haul perishables and the refrigeration unit fails, standard cargo does not pay. You need a reefer breakdown endorsement, and it must be listed on the policy.
- Unattended vehicle theft. Many policies exclude theft if the truck was left unattended — or require specific anti-theft devices. A load stolen from an unguarded lot at 2 a.m. may not be covered.
- Certain commodities. Electronics, pharmaceuticals, alcohol, tobacco, and high-value goods are often excluded or sub-limited unless scheduled.
- Improper securement. If the load shifted because it wasn't strapped or blocked correctly, the insurer can deny the claim.
How much cargo limit do you need?
Most brokers require $100,000 in cargo coverage as a baseline. But the right number is the value of the most expensive load you'll ever haul — not the average one. If you pull a $250,000 load of electronics on a $100,000 policy, you're personally exposed for the difference.
Refrigerated and high-value freight commonly requires $150,000 to $250,000 or more.
What it costs
For a Texas owner-operator with one tractor, cargo coverage typically runs $400 to $1,800 per year for $100,000 in coverage, depending on commodity, radius, and loss history. It's usually bundled with your liability and physical damage policy.
The bottom line
Cargo insurance is cheap compared to one denied claim. Match your limit to your most valuable load, add reefer breakdown if you haul perishables, and read the theft exclusions before you park for the night. If you're not sure what your policy actually covers, that's exactly the conversation to have with an independent agent before your next load.